After several years of disruption across every link of the construction value chain, supply chain stability has moved from a back-office logistics concern to a boardroom priority throughout the global building materials market. Volatile resin prices, shifting freight conditions, uneven regional demand, and energy cost swings have forced manufacturers, distributors, and contractors to rethink how decorative wall solutions — from WPC wall panels to UV marble sheets and carbon crystal wall panels — are sourced, produced, and delivered. For the wall panel segment in particular, where project timelines are tight and customization is common, the ability to guarantee consistent material flow has quietly become a decisive competitive differentiator.
Key Takeaways
• Raw material volatility — especially PVC resin, wood fiber, and energy costs — remains the largest single source of price fluctuation in the wall panel supply chain.
• Leading manufacturers are pursuing vertical integration, dual sourcing, and smarter inventory strategies rather than passing every cost swing downstream.
• Buyers are shifting from spot purchasing toward long-term supplier partnerships built on financial transparency and verifiable production capacity.
• Regional diversification of sourcing and warehousing is expected to accelerate, reducing dependence on any single trade lane or production hub.
Raw Material Sourcing Pressures Test Supply Chain Stability
The stability of any building materials supply chain begins at the raw material level. WPC wall panels depend on a blend of wood or bamboo fiber, PVC or polyethylene resin, and calcium carbonate — each exposed to different market forces. PVC resin pricing tracks crude oil and ethylene feedstocks, while wood fiber availability fluctuates with forestry output and regional processing capacity. Energy-intensive processes such as extrusion, calendering, and hot-press lamination add another layer of sensitivity, since electricity and gas costs vary widely across manufacturing regions.
Decorative surface products face particular exposure. A UV Marble Sheet manufacturer, for example, must secure not only a stable supply of calendered PVC base film but also consistent inputs of printing inks, protective wear layers, and adhesives to keep gloss, texture, and color within specification. If any one input is delayed, entire production batches can stall, extending lead times precisely when project schedules are tightest. This input interdependence explains why sheet-based decorative products often show price and lead-time swings earlier than bulk commodity materials.
Logistics compounds these pressures. Container freight rates on major East–West trade lanes have swung dramatically in recent years, and rerouting around key maritime chokepoints continues to add cost and unpredictability. Because wall panels are bulky and relatively low in density, freight can represent a meaningful share of landed cost, which makes route reliability nearly as important to buyers as ex-works pricing. A factory-level price advantage can disappear quickly if shipping conditions deteriorate mid-contract.
How Manufacturers Are Building Resilience Through Integration and Planning
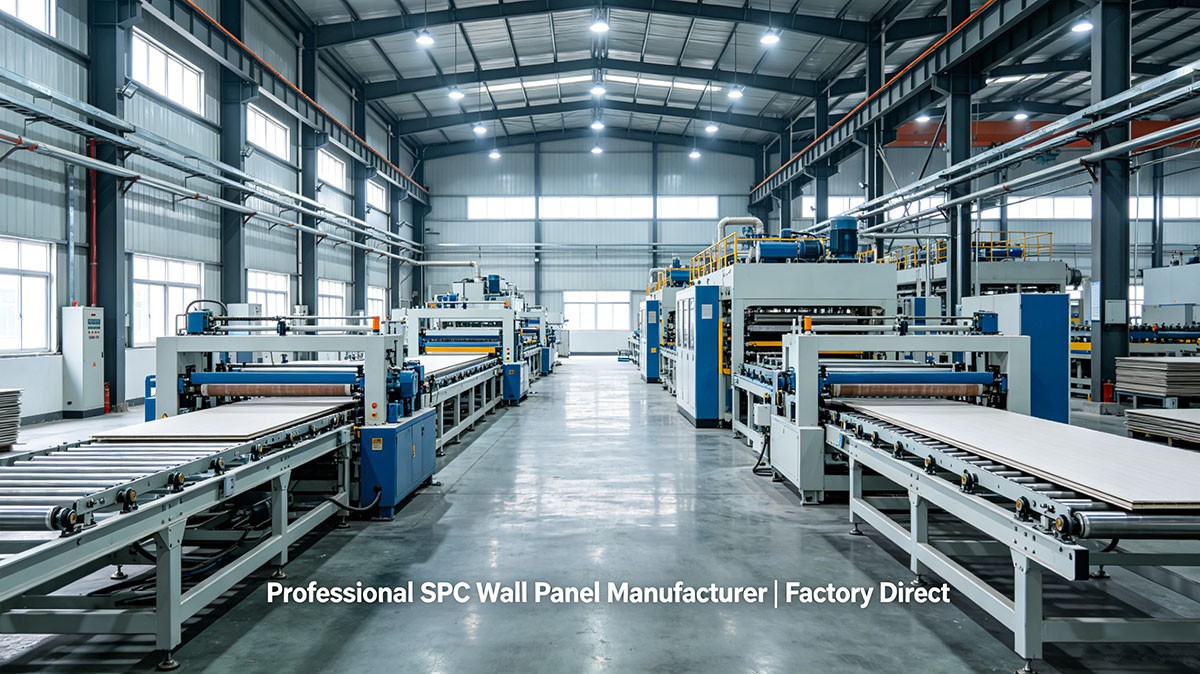
Across the industry, the response to fluctuation has shifted from reactive price adjustments to structural resilience. The most visible strategy is vertical integration: producers increasingly bring compounding, granulation, film printing, and profile extrusion in-house rather than depending on external vendors for each stage. Owning upstream processes gives manufacturers direct control over formulation quality and insulates them from short-term shortages of compounded pellets or decorative films.
Diversified sourcing is the second pillar. Rather than relying on a single resin grade or fiber supplier, mature producers qualify multiple alternatives and maintain flexible formulations that can adapt to available feedstocks without compromising mechanical performance or surface quality. Inventory strategy completes the picture: buffer stocks of critical inputs and fast-moving finished profiles trade working capital for delivery certainty — a trade many manufacturers now consider worthwhile.
Newer product categories illustrate the point well. A Carbon Crystal Wall Panel factory depends on tightly controlled lamination of composite core layers and decorative films, where even small substrate variations affect flatness, bonding strength, and edge finishing. Factories that consolidate extrusion and hot-pressing under one roof can lock in process parameters and reduce dependence on outside substrate vendors — an advantage that becomes especially visible when market conditions deteriorate. Digital procurement tools and demand-forecasting systems further help production planners anticipate shortages weeks in advance, converting what was once firefighting into scheduled risk management.
Buyer Strategies: Selecting Suppliers in a Volatile Market
For importers, distributors, and project contractors, supplier evaluation criteria have evolved in step with these changes. Price lists alone no longer reveal whether a supplier can deliver through turbulence. Professional buyers increasingly examine production capacity depth, in-house processing capability, quality certifications, financial stability, and the transparency of quoted lead times before committing volume.
Product-specific requirements sharpen the assessment. When shortlisting a WPC Fluted Wall Panels supplier, for instance, buyers audit extrusion line capacity, mould availability across profile depths, color-matching consistency between batches, and whether finished-goods stock programs exist for fast-moving designs. Fluted profiles are unforgiving of dimensional drift — their shadow lines expose even minor tolerance variations — so process discipline at the supplier is directly observable in the installed result. Technical claims can be cross-checked against independent WPC wall panel product guides and interior wall cladding design resources before contracts are finalized, reducing the risk of costly mismatches between specification and delivery.
Contract structures are changing as well. Long-term framework agreements with defined price-adjustment mechanisms are replacing pure spot purchasing, giving both sides predictability when input costs move. At the portfolio level, distributors are spreading orders across multiple origins and maintaining regional warehousing, so that a disruption in one lane or factory no longer halts an entire project pipeline. In effect, buyers are applying the same resilience logic that manufacturers adopted internally.
Conclusion and Outlook
Supply chain stability is no longer a given in the global building materials market — it is a capability that must be deliberately engineered. The wall panel sector illustrates the broader shift underway across the industry: commercial value is migrating toward manufacturers who can demonstrate verifiable control over inputs, processes, and logistics, not merely competitive pricing. Looking ahead, expect continued consolidation among mid-sized producers, deeper integration between suppliers and large buyers, growing traceability requirements tied to sustainability compliance, and gradual diversification of production footprints across regions. Companies that treat stability as a product feature in its own right — alongside design, quality, and price — will be the ones best positioned when the next wave of fluctuation inevitably arrives.
FAQ
Q: Why has supply chain stability become a critical issue in the global building materials market?
A: Modern construction projects run on tight schedules and narrow margins, so disruptions in raw materials, energy, or shipping translate directly into delayed deliveries and cost overruns. Manufacturers and buyers now treat supply chain stability as a core purchasing criterion alongside price and design.
Q: How do raw material price fluctuations affect wall panel production?
A: WPC and PVC-based wall panels rely on resin, wood fiber, calcium carbonate, and energy-intensive processing. When resin or energy prices rise, production costs climb quickly, and suppliers without diversified sourcing or inventory buffers must either absorb reduced margins or pass increases on to buyers.
Q: What should buyers look for when evaluating a wall panel supplier?
A: Key indicators include production capacity depth, in-house processing such as compounding, extrusion, and lamination, quality certifications, financial stability, transparent lead times, and finished-goods stock programs. Suppliers with vertical integration are generally better equipped to maintain consistency during market fluctuations.
Q: Are building materials manufacturers moving production closer to end markets?
A: Regional diversification is accelerating across the industry. Many companies are establishing multi-origin production or regional warehousing to reduce dependence on long trade lanes, balancing the cost advantages of concentrated manufacturing hubs against the resilience benefits of proximity.
Ready to elevate your next project? Get free samples today and experience the quality firsthand.